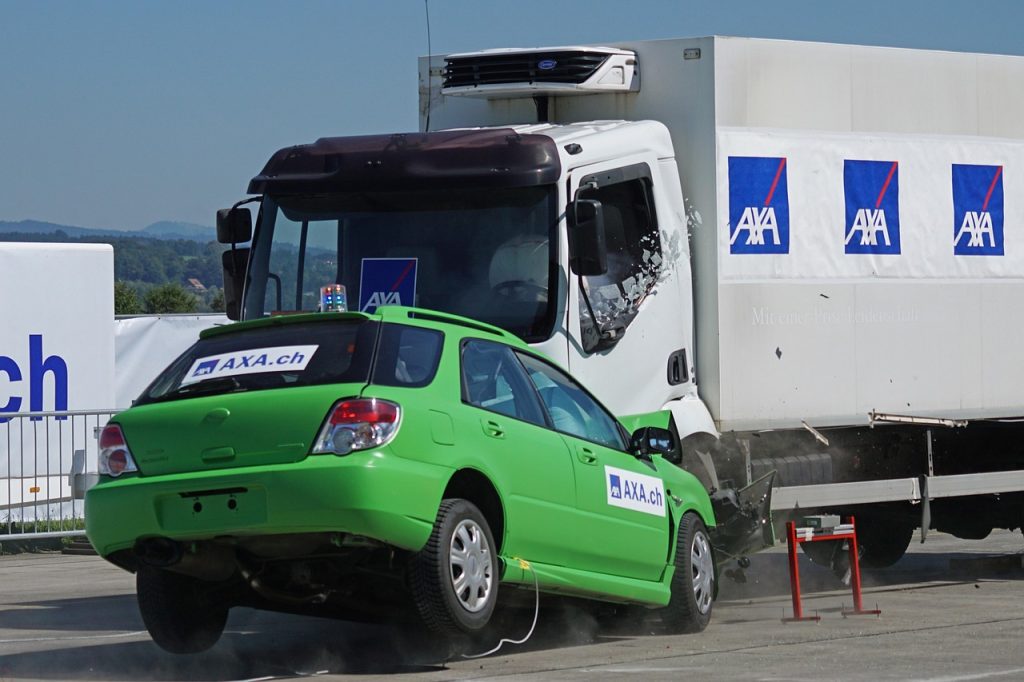
Many drivers opt for the minimum required coverage to comply with legal regulations, but this may not be sufficient in the event of an accident. If you find yourself at fault, or if damages exceed your coverage limits, you could face significant personal financial risk. Evaluating whether your liability insurance is adequate to cover potential claims is essential in protecting your assets and ensuring peace of mind on the road.
Navigating the waters of auto insurance can be quite daunting. With various types of coverage to consider, one pivotal element stands out: liability insurance. This coverage is not just a legal requirement in most states; it serves as a financial safety net in case of accidents. But the pressing question arises: is your liability insurance sufficient to shield you from potential claims?
Comprehensive Liability Insurance
Liability insurance is designed to protect you if you are found at fault for causing bodily injury or property damage to another party in an accident. It is divided into two main components:
- Bodily Injury Liability: This covers medical expenses, lost wages, and even legal fees for injuries sustained by others in an accident for which you are responsible.
- Property Damage Liability: This compensates for damages you cause to someone else’s property, such as their vehicle or a fence.
Why Liability Insurance Is Essential
One of the crucial aspects of understanding liability insurance is recognizing that it pays for the damages inflicted on others, not for your own injuries or repairs to your vehicle. If you’re involved in a serious accident, the financial consequences can be staggering, and without adequate liability coverage, you could face devastating out-of-pocket expenses.
Minimum Coverage Requirements
Each state has legal minimums for liability insurance, which may not encapsulate the full extent of potential damages. For example, a common standard might be represented as 25/50/25, which entails:
- 25: $25,000 for bodily injury liability per person
- 50: $50,000 for total bodily injury liability per accident
- 25: $25,000 for property damage liability per accident
While these limits may fulfill state requirements, they often fall short in high-cost scenarios, especially considering the rising healthcare expenses and the increasing valuation of vehicles on the road.
Assessing Your Coverage Needs
Determining how much liability insurance you need requires a moment of introspection. Consider the following:
- Your Assets: If you own a home, savings, or other valuable possessions, assess how much coverage you might need to protect these assets in the event of a claim.
- State Requirements: Familiarize yourself with your state’s laws regarding minimum coverage so you can make informed choices.
- Potential Risks: Evaluate your lifestyle and driving habits. Are you frequently on high-traffic roads or tend to drive long distances?
The Risks of Inadequate Coverage
Driving with insufficient liability coverage can be akin to flirting with disaster. If an accident leads to significant medical bills and property damage exceeding your policy limits, you may find yourself wishing you had opted for higher coverage.
Consider the example of a three-car pile-up. If you are determined to be at fault and responsible for $150,000 in damages, but your policy covers only $50,000, the remaining $100,000 could be your liability, and it might even lead to a lawsuit.
What Does Liability Insurance Not Cover?
While liability insurance is crucial, it’s equally important to be aware of its limitations:
- Repairs to your own vehicle are not covered under liability.
- Medical expenses incurred by you or your passengers might not be paid out if you are at fault.
- Damages caused by natural disasters or theft are outside the scope of liability coverage.
If you rely solely on liability insurance, you may want to consider adding collision and comprehensive coverage to fill the gaps in your protection.
Enhancing Your Protection
If you have substantial assets or ambitions, consider increasing your liability limits beyond the state minimum. Aim for limits such as 100/300/100 or higher. This would provide:
- $100,000 for bodily injury to one person
- $300,000 for total bodily injury per accident
- $100,000 for property damage
Moreover, enhancing your coverage could alleviate worries about potential legal claims and financial surprises following an accident.
Umbrella Insurance: A Broader Shield
For those with significant assets, an umbrella policy can be invaluable. This supplemental insurance kicks in when your primary liability limits are depleted, providing an additional layer of protection against lawsuits.
Should you want to delve deeper into optimizing your insurance policy and making informed decisions, look no further than Florida City Insurance, providing tailored solutions suited to your needs.